At the end of July, the American box office had its biggest opening weekend in history. Spider-Man: Brand New Day and The Odyssey landed within two weeks of each other and exhibitors found themselves with a problem they had not had for six years: not enough auditoriums.
AMC, the largest chain in the world, reported the highest single-weekend revenue and its best-attended weekend of the decade, with more than 10.2 million people passing through its AMC and Odeon sites. Spider-Man crossed a billion dollars worldwide in six days.
Here is the same year from a different angle. Through the first thirty weeks of 2026, American cinemas sold roughly 471 million tickets. Over the same stretch of 2019, they sold roughly 747 million. Footfall data from Placer.ai tells the same story from the other end: attendance is up 8.1% on last year and down 27% on 2019.
Both of these things are true, and the industry has spent the summer trying to decide which one to believe. While some believe people have come back to the cinema, some believe that it’s a case of fewer people paying more. Revenue growth in public screenings has been driven by ticket and concession prices for years now, and 2026 was simply profitable enough to be perhaps mistaken for a recovery.
Reuters made this argument in early August and it is, by now, the consensus. However, the more interesting question is not whether the box office is back, but rather what a theatrical release is now for? Let me explain why.
Consider the marketing investment behind two of this year’s successes. The Devil Wears Prada 2 opened on the first of May across 4,150 North American cinemas, took $77m domestically and $233.6m worldwide in three days (the second-biggest global debut of the year) and finished at around $676m. It cost roughly $100m to make, and roughly $80m to market. That is four-fifths of the production budget, spent again, on making sure you knew the film existed.
It also worked for “Wuthering Heights”, which is the more instructive case, because on paper it should not have. Emerald Fennell’s adaptation opened over Valentine’s weekend to $34.8m domestically (under the $35–45m that Box Office Pro had projected), earned a B CinemaScore from audiences and divided critics badly. It went on to take $242m worldwide against an $80m budget, and finished as the seventh highest-grossing film of the year. USA Today, reporting the opening, credited the press tour directly: a campaign of considerable heat that ran for weeks and turned a nineteenth-century novel into an event with a dress code.
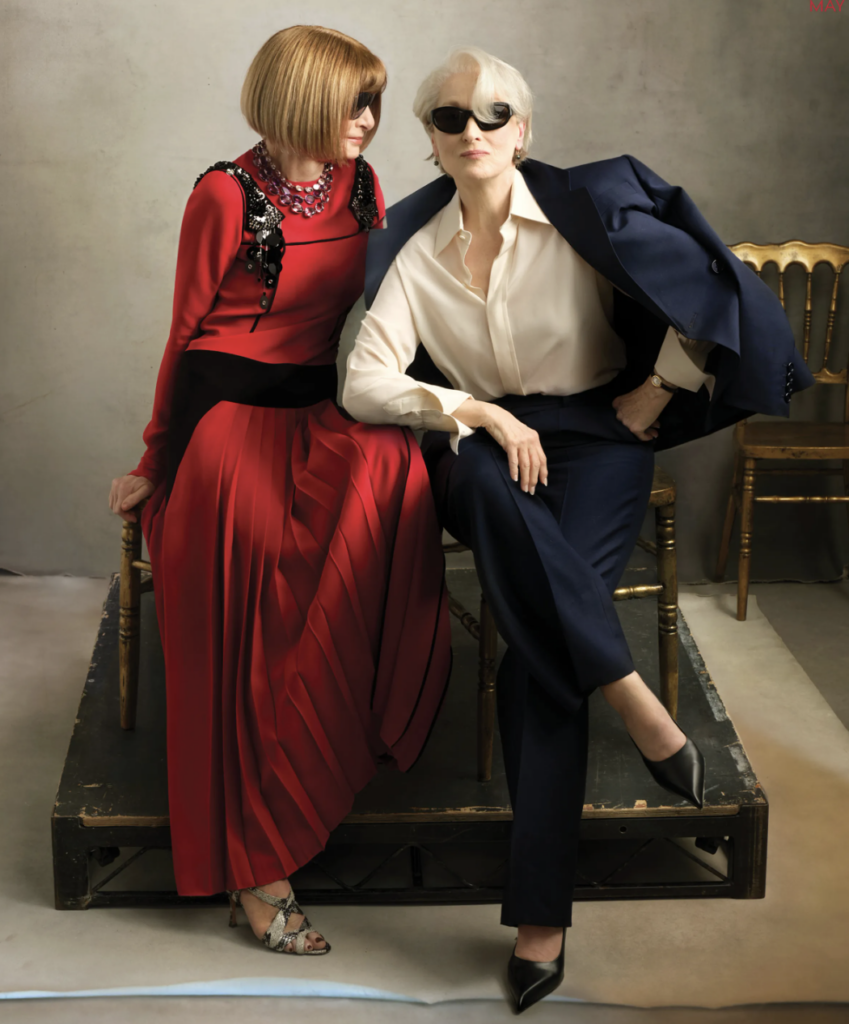
Some of that is conventional, like trailers, outdoor, or digital buys. But an increasing share of it is the thing that has become the actual apparatus of a modern release: the press tour as a sustained cultural event. Reunion photography, red carpets covered as fashion rather than film, magazine campaigns that function as trailers with better lighting (we won’t forget the Anna Wintour and Meryl Streep elevator-moment anytime soon). For six weeks before the film opened, the promotional layer was itself the content, generating more coverage, more clips and more discourse than the film would generate in its opening month, and it worked.
The counter-example arrived last autumn. Like “Wuthering Heights”, the film had prestige literary adaptation, a big name director, a star cast, and a sizable budget.
Guillermo del Toro’s Frankenstein cost around $120m. Netflix put it into cinemas for a few days with no meaningful promotional campaign behind the theatrical window, and it took about $129,000 in American cinemas. Del Toro had said publicly that the film belonged on a big screen, but the company that financed it had no commercial reason to agree, because its business is the subscription, not the seat.
Set the two films side by side and the lesson is that a theatrical release is now an expensive discretionary event that a company either chooses to stage or chooses not to. Warner Bros. outbid Netflix for “Wuthering Heights” on the strength of a guaranteed wide release, and then spent to make the release matter. Netflix had Frankenstein and declined to.
Cinema is being converted from an automatic distribution step into a purchasable marketing product. But what is the marketing actually marketing?
In November 2025, A24 opened branded retail spaces inside Barnes & Noble: custom-designed sections curated by the studio, stocking its books, Blu-rays, vinyl, collectibles and exclusive merchandise, launched in nine stores with more rolling out through 2026. It was the first physical retail destination in A24’s history (the online shop dates to 2017, the publishing arm to 2019) and, according to Barnes & Noble, the first time the chain had partnered with a brand on this kind of activation nationally. The partnership extends to in-store events; the launch of Eleanor Coppola’s posthumous memoir featured Sofia and Roman Coppola in conversation, moderated by a Vogue editor.
One could almost argue that A24 is not a studio that sells merchandise so much as a consumer brand with a film division attached, and the films are the most effective advertising the brand has. The screenplay collection, the hardcovers, the Blu-rays with the good packaging, the crossword book, the candle… these are not ancillary revenue in the old sense of a licensing deal struck after a hit, but rather, they are the point.
At the very least, the strangeness of the current moment (with the enormous press tours, the world-building, and the sense that the campaign is more designed than the film) suggests that the film industry is undergoing a transition whereby everything surrounding a film matters at least as much (sometimes more) than the film itself. The best illustration is the Barbie universe created in the lead-up to the 2023 Greta Gerwig-produced film, which more than 100 brands tapped into; Airbnb created a life-sized Barbie mansion, Burger King in Brazil created pink burgers, Crocs launched Barbie shoes, and so on. The rollout created an inescapable lifestyle wave that made the actual box-office juggernaut feel almost secondary to the aesthetic trend it sparked.

If launching a film requires an $80m attention campaign, the field narrows to the companies that can write that cheque, and the numbers already show it: Universal, Disney, Sony, Warner Bros. and Paramount came out strong this year.
That concentration is about to be tested. Paramount Skydance agreed in February to acquire Warner Bros. Discovery, but they were sued, with the litigation arguing about the right thing: not whether the films will be good, but how many companies will be in a position to make them at scale. Consolidation is not what made the attention economy expensive; the attention economy became expensive, and consolidation is what follows when only five companies can afford it.
Within two or three years, the theatrical release for most studio films will be understood internally as a marketing expense rather than a revenue line (i.e. a campaign that launches a brand, a franchise and a merchandising catalogue) while a smaller number of premium event films carry the actual theatrical economics on inflated ticket prices. The screen stops being the only place where money is made and becomes the reason the money can be made elsewhere.
What is interesting is that 2026 keeps producing evidence against it. The year’s most interesting box office stories have not been franchise instalments; Project Hail Mary opened to $80m in March and held with unusually shallow weekly drops, and Obsession and Backrooms were surprise hits that nobody predicted. Variety’s reporting on the rebound credits Gen Z and argues that studios are now more willing to back unorthodox material because they have watched it work. “Wuthering Heights” itself — an original-ish literary adaptation with mixed reviews and no pre-existing universe — is not the behaviour of an industry that has given up on distinctiveness.
I do not think that disproves the thesis so much as locate its limit. The audience still rewards films that feel like specific objects rather than interchangeable units of engagement. What has changed is that being recognised as a specific object now costs $80m, and the number of organisations that can pay is falling. Both halves can be true, and the uncomfortable version of the future is the one where they stay true simultaneously: better films, fewer makers, higher prices, smaller rooms.
What a major box-office launch has become and requires, and how that is changing the cinema industry, mirrors what we see happening with consumer brand strategy. That is, those with “the best show” have a huge competitive advantage in arenas where cultural capital are drivers of brand relevance and sustained growth.
Your product (the film) needs to be developed and delivered holistically with other elements beyond traditional attention mechanisms (the launch). To the point where they feel, and are, an integral part of the product and brand. This level of applied holistic strategy is what enables cultural relevance and other revenue streams.
Sustaining that level of holistic delivery requires greater, sustained creativity and organisational collaboration. The film industry is providing another example of what modern marketing and branding is, does and requires.
135 W 41st St 5th Floor
New York NY 10036
+1 (212) 518-3444
Buspace
London
W10 5AP
